
Yesterday I wrote the same guide for Chase Ultimate Rewards, and it ended with the obvious next question. Amex points or Chase points: which are worth more?
Start with the part that surprises most people. An Amex point has the lowest cash floor of the four major transferable currencies. Cover Your Charges pays 0.6 cents per point. Those same points can be worth 1.1 cents in cash through the Schwab Platinum, about 1.5 cents through the Business Platinum’s airline bonus, and 2 cents or more through airline transfers. The gap between the worst and best redemption is the widest in the game. With Amex, the card you redeem through and the method you pick matter more than anywhere else.
Quick heads up: this post mentions credit cards, and some links are affiliate links. If you apply through them, I may earn a commission at no extra cost to you. It keeps the guides free.
In this guide: the exact value of every Amex redemption option per Amex’s own published numbers, the Schwab and Business Platinum power plays, a 100,000-point worked example across five redemption types, and the mistakes that quietly cost people half their value.
Click here for the best cards with the highest welcome offers.
My best Amex redemption: Etihad business class for four
Numbers are abstract until they are your family in lie-flat seats. So here is mine.
I booked all four of us in Etihad business class from Toronto to Abu Dhabi with Flying Blue miles I transferred from Amex. Amex transfers 1:1 to Flying Blue, so 80,000 Amex points became 80,000 Flying Blue miles, and each ticket cost about $250 in taxes and fees.
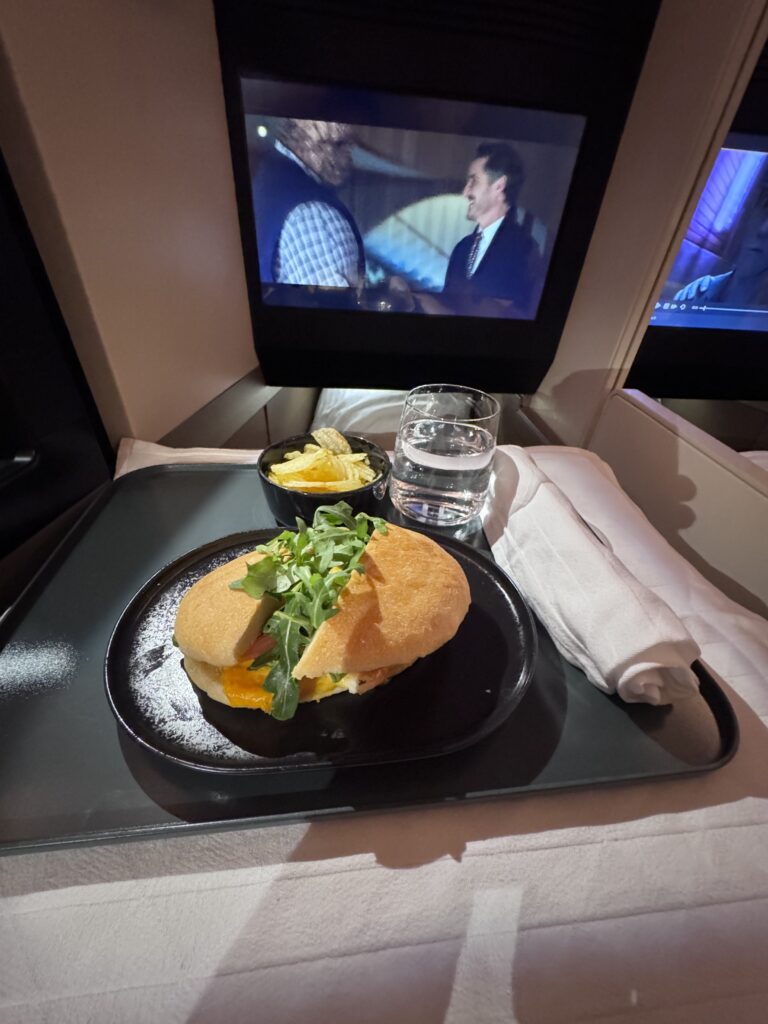
The cash price for that exact seat runs $2,000 to $3,000 each way. On the low end: $2,000 minus $250 in taxes, divided by 80,000 points, is about 2.2 cents per point. On the high end it is closer to 3.4 cents. Either way it is roughly triple what Amex hands you for cashing out.
You can read the full flight review here: Etihad A380 Business Class Review (YYZ-AUH)
And that is just one of several Amex redemptions I have made over the years.
What an Amex point is worth: every redemption, ranked
| Redemption | Value per point | Who gets it |
|---|---|---|
| Cover Your Charges | 0.6 cents | Every card; the floor |
| Pay with Points at checkout | 0.7 to 1 cent | Every card; select retailers |
| Prepaid hotels, Amex Travel | 0.7 cents | Every card |
| Gift cards | up to 1 cent | Every card; varies by brand |
| Flights, Amex Travel | 1 cent | Every card |
| Schwab cash-out | 1.1 cents | Schwab Platinum; first 1M points per year |
| Business Platinum 35% airline bonus | about 1.5 cents | Business Platinum; flights via Amex Travel |
| Transfer to airline and hotel partners | varies; often 2+ cents | Best ceiling; one way transfers |
Rates verified October 2026 against Amex’s published redemption values. Transfer values depend on the award you book and the cash price it replaces.
The seven ways to use Amex points, ranked by value
7. Cover Your Charges: 0.6 cents
This is the floor, and it is a bad one. Using points to erase statement charges pays 0.6 cents per point, meaningfully below Chase’s 1 cent floor and below every other major currency. 100,000 points here become $600. The same points cashed through the Schwab Platinum would be $1,100.
The rule of thumb: never accept less than 0.6 cents per point, and treat 0.6 as a warning, not a target.
6. Prepaid hotels through Amex Travel: 0.7 cents
Prepaid hotel bookings through the Amex Travel portal redeem at 0.7 cents per point. 50,000 points get you $350 toward a hotel. It beats the floor, but barely, and prepaid portal bookings generally do not earn hotel points or elite night credit. For hotels, this is almost never the right call unless you have no better option.
5. Pay with Points at checkout: 0.7 to 1 cent
Amex lets you redeem points directly at checkout with select retailers and food delivery services. Amex’s own example: 10,000 points get you $70 at select online retailers, about 0.7 cents per point. The upper end of the range applies to specific partners. This is the single most tempting way to torch your points for less than they are worth. The button is convenient. The math is not.
4. Gift cards: up to 1 cent
Redeeming for gift cards pays up to 1 cent per point. Amex’s example: 5,000 points for up to $50 depending on the brand. That “depending on the brand” is doing real work. Some brands pay the full cent, others pay less. Check the redemption rate on the specific card before you commit.
3. Flights through Amex Travel: 1 cent
Flights booked through American Express Travel redeem at a flat 1 cent per point. 50,000 points cover a $500 plane ticket. This is the honest simple option: no award charts, no availability hunting, and flights booked through the portal earn airline miles and elite qualifying credit like cash tickets.
For the traveler who does not want to learn award charts, 1 cent through the portal is a respectable floor. It is also the benchmark every other redemption has to beat.
2. The two Platinum power plays: 1.1 and about 1.5 cents
Two specific cards raise the simple redemption ceiling, and they change the answer to “how much is an Amex point worth” more than anything else in the program.
Schwab Platinum: 1.1 cents in cash. The Platinum Card from American Express for Charles Schwab lets you deposit points directly into an eligible Schwab account at 1.1 cents each through the Invest with Rewards feature, on the first 1 million points per calendar year. After that the rate drops to 0.8 cents. Because Membership Rewards pool across all of your own Amex cards, points earned on a Gold or Green get the same 1.1 cent cash-out rate once the Schwab Platinum is in your wallet. 100,000 points become $1,100 in real money. This is the best cash value in the transferable points game, and it is not close.
Business Platinum: about 1.5 cents through the 35% airline bonus. Get 35% of your points back when you redeem through Amex Travel for flights with your selected airline, or for first and business class flights on any airline. The math works out to roughly 1.5 cents per point. It only works through Amex Travel, and it requires the premium card, but for heavy travelers booking paid premium fares it is the highest no-chart value available.
1. Transfer to airline and hotel partners: the ceiling
Twenty airline partners and a handful of hotel partners, most transferring 1:1. This is where Amex points earn their reputation, and the lineup is the deepest in the industry: ANA Mileage Club, Virgin Atlantic Flying Club, Air Canada Aeroplan, Flying Blue, Qatar Privilege Club, Singapore KrisFlyer, British Airways, Avianca LifeMiles, Cathay, and more, plus Hilton Honors at 1:2, Marriott Bonvoy at 1:1, and Choice Privileges at 1:1.
The sweet spots are what make this rank first. Virgin Atlantic charges 52,500 points one way for West Coast to Japan business class, and 60,000 from Central and Eastern USA. ANA prices one-way US to Japan business from 50,000 to 82,500 points by season. Flying Blue’s Light business class from the US to Paris prices at 60,000 miles, which at Amex’s 1:1 transfer ratio is 60,000 Amex points. Qatar QSuites from JFK to Doha goes for 70,000 Avios off peak one way.
Two mechanics to know before you transfer. First, a handful of partners do not transfer at 1:1. Aeromexico is 1:1.6, JetBlue is 250:200, Emirates and Cathay transfer at 5:4. Check the ratio in your Amex account before moving points. Second, Amex charges an excise tax offset fee of $0.0006 per point, capped at $99, on transfers to US airline programs, which for Amex means Delta SkyMiles and JetBlue TrueBlue. International partners carry no fee, which is one more reason the best value usually sits with the foreign programs.
And the standing rule: transfers are one way. Once points leave Amex, they never come back. Never transfer speculatively. Find the award, confirm the dates, then move the points.
A 100,000 point worked example
Numbers beat theory. Here is what the same 100,000 points become across the five options.
| You use 100,000 points for | What you get | Effective value |
|---|---|---|
| Cover Your Charges | $600 toward statement charges | 0.6 cents |
| Amex Travel flight | $1,000 toward a plane ticket | 1 cent |
| Schwab cash-out | $1,100 into your Schwab account | 1.1 cents |
| Transfer to Virgin Atlantic | 1 one-way business seat, West Coast to Japan, at 52,500 (47,500 points left over) | 2 cents+ when cash fares are high |
| Transfer to Flying Blue | 100,000 points become 100,000 miles at 1:1, enough for 1 one-way US to Paris business award at 60,000 miles with 40,000 left over | 2 cents+ when cash fares are high |
Virgin Atlantic prices West Coast to Japan business class at 52,500 points one way (60,000 from Central and Eastern USA). Flying Blue Light business US to Paris prices at 60,000 miles one way (Amex transfers 1:1 to Flying Blue). Transfer examples assume award availability, which moves daily.
The one rule that decides your rate
Your points are worth what your setup says they are worth.
Unlike Chase, Amex points pool automatically across all of your own Membership Rewards cards. There is no combining step and no household member to link. Points earned on a no annual fee Amex card land in the same account as points earned on the Platinum. The differentiator is not how you hold the points, it is which premium card is in your wallet when you redeem.
One thing Amex will not let you do: move your points to another person’s Membership Rewards account. No pooling with a spouse or partner the way Chase allows with a household member. Transfers to airline and hotel accounts have to go into an account in your own name.
The move, if you want one, is simple. Decide up front whether you are a transfer person or a cash-out person. If you are a transfer person, the Schwab and Business Platinum do not matter much to you; your value comes from award charts. If you are a cash-out person, the Schwab Platinum turns every Amex point you earn anywhere into 1.1 cent cash, the highest paying floor in the transferable points game.
One guardrail: points never expire while you hold at least one card enrolled in Membership Rewards and your account is in good standing. If you close your last enrolled card, move or use your points first. They vanish with the account.
The honest caveats
A point worth being honest about, because it trips people up: the floor is worse than you think.
0.6 cents is the worst floor of the four currencies. Chase pays 1 cent for cash back. Capital One pays 1 cent. Citi pays 1 cent. Amex pays 0.6. The penalty for a lazy redemption is bigger with Amex than anywhere else. Cover Your Charges turns a healthy points balance into mediocre money.
Transfer value is a quote, not a promise. When someone says Amex points are worth 2 cents, they are usually describing their own past redemptions. Your value depends on the award you find and the cash price it replaces. A sweet spot price in an award chart is not a promise that seats exist on your dates. Check availability before you transfer, because transfers do not reverse.
The excise fee is real but small. Transfers to Delta and JetBlue carry a fee of $0.0006 per point, capped at $99. On a 100,000 point transfer that is $60. It is not a reason to avoid transfers, but it is a real line item, and it is one more reason the foreign partners usually win.
Programs devalue. The transfer lineup is a strength, and it is not permanent. Programs reprice, ratios shift, and partners leave. Every valuation in this post describes the programs as they exist today. Hoarding points for years is how you watch the ceiling come down on you.
The portal is not always the cheapest price. Amex Travel inventory can price higher than booking direct, and prepaid hotel bookings there generally do not earn hotel points or elite night credit. The 1 cent flight rate is only a deal if the underlying price is fair. Compare the cash price before you burn points.
My take
Treat 0.6 cents as the floor, 1 cent as the honest benchmark, and 2 cents as the target. If a redemption gets you under 1 cent per point, cash it through the Schwab Platinum instead if you have one, or book it as a flight through Amex Travel. If it gets you near 2 cents with a transfer you understand, take the points and move on.
The one thing I would actually do: decide which redemptions you will realistically use, then make sure you hold the card that unlocks them. A stash of Amex points with no plan is the most common way to end up cashing out at 0.6 cents, which is the worst deal in the currency.
Frequently asked questions
Do Amex Membership Rewards points expire?
No. Points do not expire as long as you hold at least one card enrolled in the Membership Rewards program and your account is in good standing. If you close your last enrolled card without using or transferring your points, they are forfeited.
Can I combine Amex points with a spouse or partner?
No. Amex points cannot be transferred to another person’s Membership Rewards account. Transfers to airline and hotel loyalty programs must go into an account in your own name. Your own points do pool automatically across all of your Amex cards.
What is the best use of Amex Membership Rewards points?
For maximum value, transfer to airline partners for premium cabin awards, where 2 cents per point or more is realistic on the right route. For simplicity and cash flexibility, the Schwab Platinum cashes points out at 1.1 cents into an eligible Schwab account, the best cash rate of any transferable currency.
Are Amex points worth more than Chase Ultimate Rewards points?
It depends on where you travel and how you redeem. Chase’s edge is World of Hyatt and simple high value portal redemptions through Points Boost. Amex’s edge is the deeper airline partner lineup, the 1.1 cent Schwab cash-out, and sweet spots like Virgin Atlantic to Japan and ANA to Asia. Pick the currency whose partners fly where you actually go.
Do I need the Schwab Platinum to get 1.1 cents per point?
Yes. The 1.1 cent cash-out rate comes from the Platinum Card for Charles Schwab through its Invest with Rewards feature, and you need an eligible Schwab account. It applies to the first 1 million points per calendar year; points redeemed after that get 0.8 cents each.
The bottom line
An Amex point is worth 0.6 cents if you cover charges, 1 cent for flights through Amex Travel, 1.1 cents in cash with the Schwab Platinum, about 1.5 cents with the Business Platinum’s 35% airline bonus, and more than that through smart transfers to the 20 airline and hotel partners. The currency rewards a plan and punishes laziness, so decide which of those numbers you want before you redeem anything.
Related reading:
- How Much Are Chase Ultimate Rewards Points Worth?
- How to Transfer Credit Card Points to Airlines: The Beginner’s Guide
- ANA and JAL Business Class to Japan: Every Way to Book With Points
- Amex to Flying Blue 25% Bonus: Paris Business for 48,000 Points
Sixty cents is the floor. Two cents is the target. Anything in between is a choice.
View comments
+ Leave a comment